
Choosing the right life insurance policy is an important financial decision because it affects both long-term savings and financial protection for your family. India has several life insurance options, but Postal Life Insurance (PLI) and Life Insurance Corporation of India (LIC) are two well-known choices. When comparing PLI vs LIC, it is important to look beyond premium rates and consider eligibility, policy features, bonuses, maturity benefits, flexibility, and your long-term financial objectives.
Both PLI and LIC offer life insurance products designed to provide financial security, but they serve somewhat different customer groups. Understanding these differences can help you decide which option is more suitable for your circumstances.
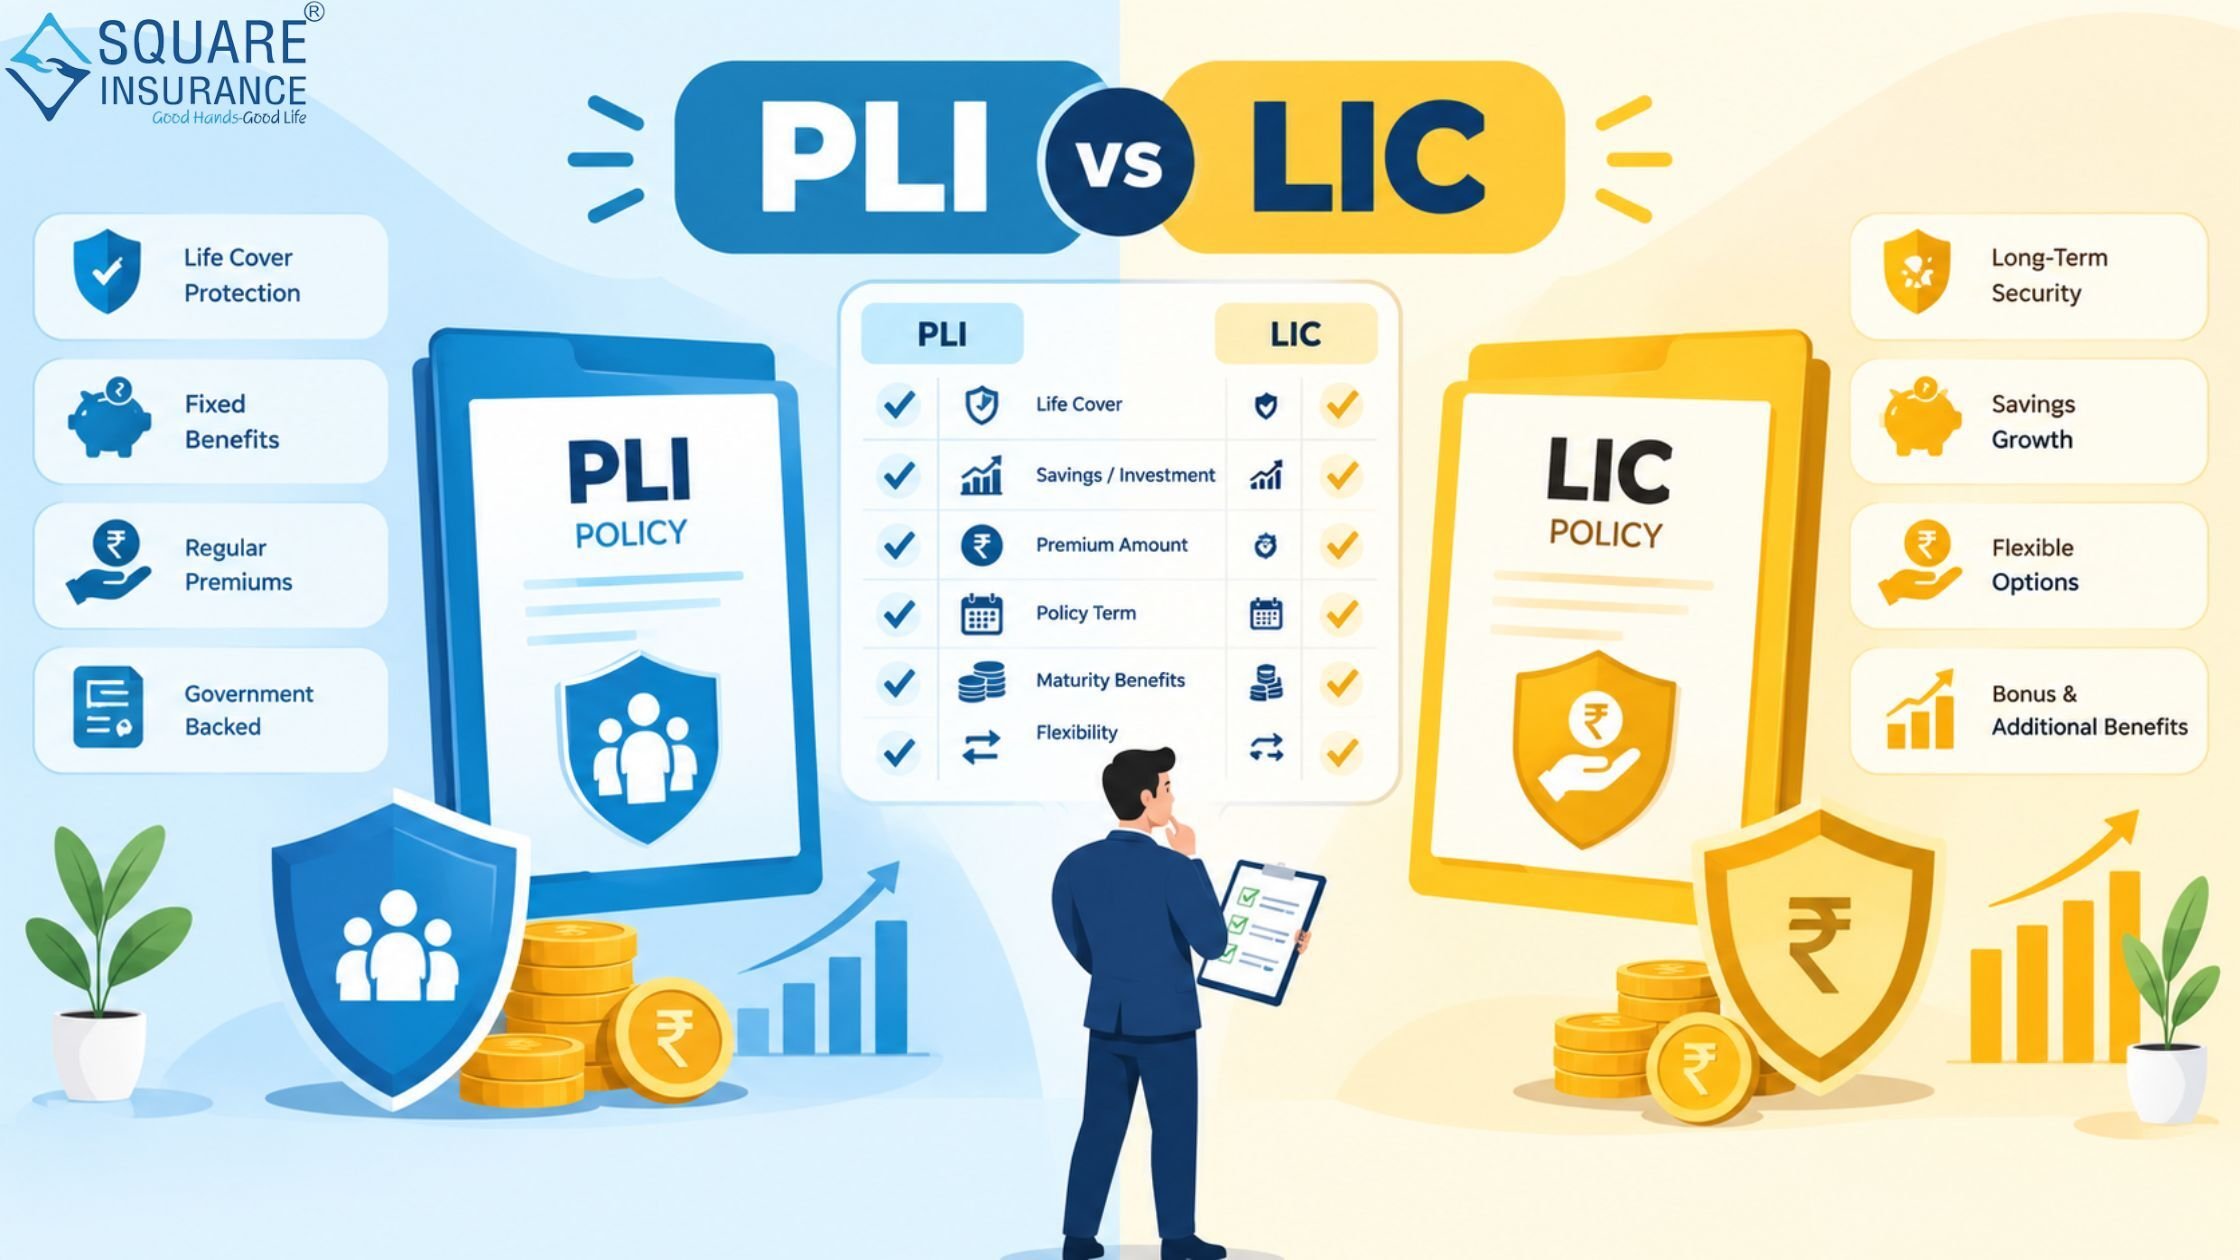
What is Postal Life Insurance (PLI)?
Postal Life Insurance is a life insurance service associated with India Post. It was introduced primarily to provide insurance coverage to eligible employees and certain other approved categories. Over time, PLI has expanded its reach while continuing to focus on providing life insurance with savings-oriented benefits.
PLI offers different types of policies, including protection and savings-based plans. Depending on the policy selected, policyholders may receive benefits such as life cover, maturity proceeds, bonuses and loan facilities.
One of the notable characteristics of PLI is its focus on eligible groups and relatively straightforward policy structures. It can be particularly relevant for people who meet its eligibility criteria and prefer a traditional life insurance product.
What is LIC?
Life Insurance Corporation of India, commonly known as LIC, is one of India's largest and most established life insurance providers. It offers a broad portfolio of life insurance products for individuals with different financial requirements.
LIC provides various categories of policies, including term insurance, endowment plans, money-back policies, whole-life plans, pension-oriented products and other insurance solutions.
Because of its wide product range, LIC can accommodate different objectives, such as pure protection, long-term savings, retirement planning and financial planning for specific life goals.
PLI vs LIC: Key Differences
The difference between PLI and LIC is not simply about which insurer is better. The more useful question is which one fits your eligibility, coverage requirements and financial goals.
1. Eligibility
PLI policies are generally available to specific eligible categories as defined under its rules. Eligibility should therefore be checked before applying.
LIC, on the other hand, offers products to a much broader section of the population, subject to the eligibility requirements of the selected policy.
Key takeaway: If you do not qualify for PLI, LIC may provide a wider range of alternatives.
2. Policy Options
PLI provides multiple traditional insurance plans, including policies designed around endowment, whole-life and money-back features.
LIC has a significantly broader product portfolio. Customers can select from plans designed for protection, savings, income, retirement and other financial needs.
Key takeaway: LIC generally provides greater variety, while PLI can be attractive for eligible customers looking for traditional insurance and savings products.
3. Premium and Benefits
Premiums depend on several factors, including age, sum assured, policy term, plan type and applicable underwriting conditions. Therefore, it would be inaccurate to assume that PLI is always cheaper than LIC or vice versa.
The overall value should be assessed by comparing the premium against the life cover, maturity benefits, bonuses, policy conditions and other features.
4. Bonuses
Traditional participating insurance policies may provide bonuses according to the insurer's applicable declarations and policy terms.
Both PLI and LIC have traditional participating products where bonuses can contribute to the overall policy benefits. However, bonuses are not necessarily identical across products and should not be treated as guaranteed unless specifically stated as guaranteed benefits.
5. Loan Facility
Certain eligible PLI and LIC policies may provide a loan facility after fulfilling applicable conditions. This can provide liquidity during financial emergencies without immediately surrendering the policy.
However, policyholders should check the applicable loan value, interest rate, eligibility and repayment conditions before using this facility.
6. Maturity Benefits
Maturity benefits depend on the specific policy. A savings-oriented policy may provide the sum assured along with applicable bonuses or other benefits when the policy reaches maturity.
The actual maturity amount should therefore be evaluated based on the individual policy illustration and terms rather than comparing PLI and LIC only at the insurer level.
Major Benefits of PLI
PLI can be considered by eligible individuals who prefer traditional life insurance with savings components. Some potential benefits include:
- Life insurance protection for the policyholder
- Savings and maturity-oriented policy options
- Availability of different traditional policy structures
- Potential bonus additions in participating policies
- Loan facility on eligible policies
- Insurance services through the postal network
- Long-term financial planning opportunities
The suitability of a PLI policy depends on eligibility and the specific product selected.
Major Benefits of LIC
LIC's biggest advantage is the breadth of its insurance portfolio. Some important benefits include:
- Wide selection of life insurance products
- Options for pure protection and long-term savings
- Products designed for different financial goals
- Retirement and pension-oriented solutions
- Money-back and income-oriented policy options
- Potential bonuses in participating policies
- Multiple servicing and distribution channels
The exact benefits vary significantly from one LIC policy to another.
PLI vs LIC: Which is Better for You?
There is no universal winner in the PLI vs LIC comparison. The better option depends on what you need from your insurance policy.
PLI may be suitable if:
- You meet PLI's eligibility requirements.
- You prefer a traditional life insurance product.
- You are looking for long-term savings along with insurance protection.
- You value the services associated with the postal network.
- The features and premium of a particular PLI plan match your financial goals.
LIC may be suitable if:
- You want a wider choice of insurance products.
- You require a policy specifically designed for protection, savings or retirement.
- You want to compare different policy structures.
- You need a product aligned with a particular financial milestone.
- You want more flexibility in selecting among different types of life insurance plans.
How to Choose Between PLI and LIC
Before purchasing a policy, avoid making the decision solely on the basis of brand familiarity. Start by identifying your primary objective.
If your priority is family protection, examine the life cover and policy exclusions. If you are looking for savings, compare the maturity benefits, policy term and expected benefits. For retirement planning, evaluate the income or pension-related features.
You should also consider your age, income, existing insurance coverage, financial responsibilities and ability to pay premiums throughout the policy term.
Most importantly, read the policy document carefully. Check surrender conditions, exclusions, premium payment requirements, nomination provisions, loan rules and other applicable terms before making a commitment.
Factors to Compare Before Buying
A practical comparison should include:
- Eligibility: Check whether you qualify for the selected plan.
- Life Cover: Determine whether the sum assured is adequate for your family's needs.
- Premium: Ensure the premium is affordable for the entire policy term.
- Policy Term: Select a duration consistent with your financial goals.
- Maturity Benefits: Understand what you may receive at maturity.
- Bonuses: Check whether bonuses are applicable and how they are determined.
- Liquidity: Review loan and surrender provisions.
- Claim Process: Understand the documentation and process involved in making a claim.
- Policy Conditions: Read exclusions and other terms before purchasing.
- Financial Objective: Choose a plan based on your actual requirement rather than simply selecting the most popular insurer.
Frequently Asked Question (FAQs)
Q1. What is the main difference between PLI and LIC?
PLI is a life insurance service with specific eligibility criteria, while LIC offers a wide range of life insurance products to a broader customer base. Their products, eligibility conditions and benefits can differ.
Q2. Is PLI better than LIC?
Neither is universally better. PLI may be suitable for eligible customers whose requirements match its plans, while LIC can be preferable for customers seeking a wider range of insurance products.
Q3. Does PLI offer maturity benefits?
Yes, eligible PLI policies can provide maturity benefits according to the terms of the selected policy. The actual benefit depends on the plan, policy term and applicable additions.
Q4. Does LIC provide bonuses?
Certain participating LIC policies may provide bonuses as declared according to the applicable policy terms. Bonuses can vary by product and should not automatically be considered guaranteed.
Q5. Can I take a loan against a PLI or LIC policy?
Some eligible policies from PLI and LIC may offer policy loans after meeting specified conditions. Policyholders should check their individual policy documents for eligibility and applicable terms.
Conclusion
The PLI vs LIC comparison becomes easier when you focus on your own eligibility, financial objectives and required level of protection rather than simply asking which organisation is better. PLI can be a useful choice for eligible individuals seeking traditional insurance and savings benefits, while LIC offers a broader range of products for different financial requirements.
Before making a final decision, compare individual policies carefully, understand their terms and select coverage that remains affordable throughout the policy period. A well-chosen life insurance policy can provide both financial protection and support for long-term planning. Square Insurance can also help customers approach insurance decisions with greater clarity by comparing their requirements and understanding suitable policy options.